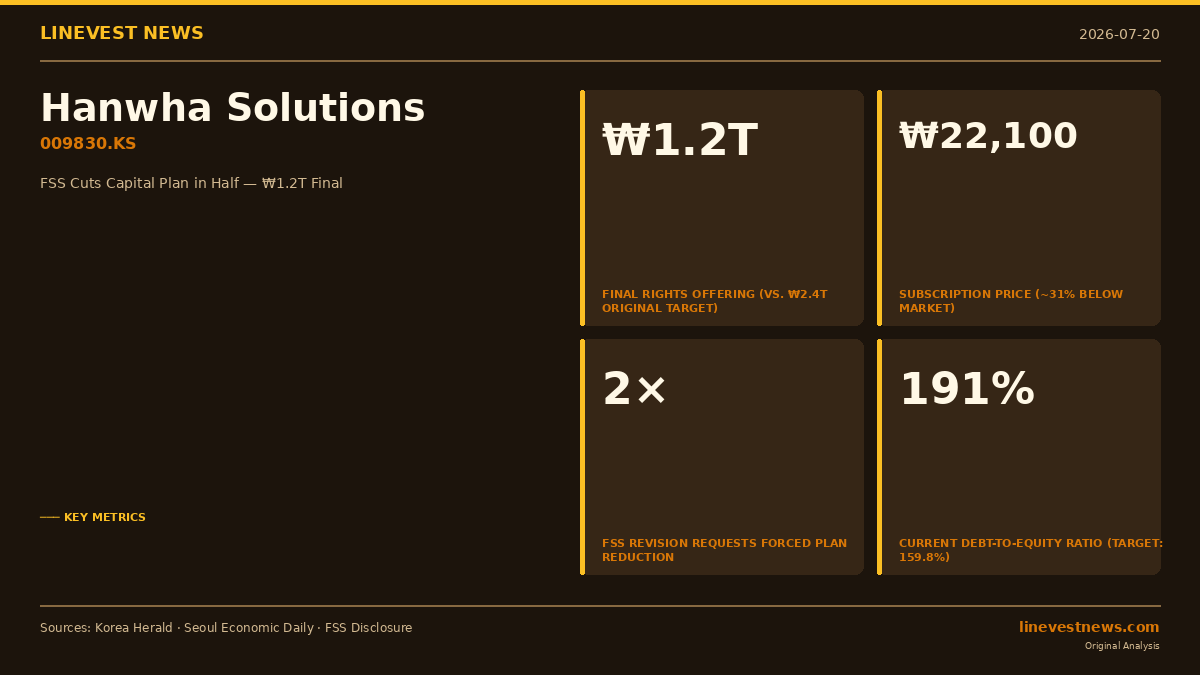
TL;DR - Hanwha Solutions (009830.KS) confirms ₩1.2 trillion rights offering — half its original ₩2.4T March target - 56 million new shares priced at ₩22,100, a 20.8% discount from the preliminary ₩27,900 and roughly 31% below the July 20 market price (~₩32,000) - South Korea's Financial Supervisory Service (FSS) demanded two rounds of revisions in April, citing thin disclosure on liquidity risk and profit outlook - Existing shareholders subscribe July 22–23; new shares list on August 11 - The ₩1.2T gap vs. the original plan will be funded from internal cash and additional US liquidity
Part A — What Was Announced
Hanwha Solutions, the solar energy and chemicals arm of the Hanwha Group, finalized the subscription price and share count for its long-delayed rights offering on July 20, 2026. Existing shareholders may subscribe at ₩22,100 per share across 56 million new shares, generating proceeds of approximately ₩1.24 trillion.
From ₩2.4 Trillion to ₩1.2 Trillion: A Four-Month Journey
The offering has been a study in regulatory friction and market adversity:
| Date | Development |
|---|---|
| March 26, 2026 | Announces ₩2.4T offering (72M new shares); ₩1.5T for debt, ₩900B for growth |
| April 9, 2026 | FSS issues first revision request — demands clearer disclosure of liquidity risk and alternative funding options |
| April 30, 2026 | FSS issues second revision request — seeks more robust medium-to-long-term profit projections |
| May 2026 | Offering scaled to ~₩1.7T; subscription price set at ₩27,900 (preliminary) |
| July 20, 2026 | Final terms confirmed: ₩1.2T, 56 million shares at ₩22,100 |
The FSS revision requests were unusually assertive. The regulator — Korea's equivalent of the SEC for securities disclosure — rarely demands multiple rewrites of a large-cap rights offering prospectus. The two revision letters focused on three issues: (1) the company's assessment of its immediate liquidity risk without the offering, (2) whether alternative financing had been fully considered, and (3) the credibility of multi-year earnings estimates underpinning the investment case.
Minority shareholders added their own pressure. From the March announcement, retail and institutional investors pushed back on the dilutive structure, arguing that the offering prioritised the founding Kim family's desire to shore up a struggling solar unit at the expense of existing holders.
Part B — What It Means for Investors
Balance Sheet Under Pressure
Hanwha Solutions entered 2026 carrying a heavy debt load. At the end of Q1 2026, total liabilities stood at ₩22.93 trillion — a debt-to-equity ratio of 191%. The company's target is to bring that ratio to approximately 159.8% by year-end, a reduction that requires both the rights offering proceeds and continued earnings recovery.
| Metric | Q1 2026 |
|---|---|
| Revenue | ₩3.88 trillion (+3.3% YoY) |
| Operating profit | ₩92.6 billion (vs. ₩11.5B consensus — 8× beat) |
| Net loss | –₩38.2 billion (vs. –₩411.2B in Q4 2025) |
| AMPC receipts (US IRA) | ₩216.1 billion (+112% QoQ) |
| Total liabilities | ₩22.93 trillion |
| Debt-to-equity ratio | 191% |
The Q1 operating profit beat was driven by a surge in US Advanced Manufacturing Production Credits (AMPC) — a US IRA provision that pays domestic solar panel makers per watt produced. Hanwha Qcells, the company's US subsidiary, has been actively monetising AMPC credits — booking ₩216.1 billion of AMPC income in Q1 2026 alone — and recently obtained a $1.45 billion DOE loan to expand its Georgia manufacturing hub.
The Funding Gap
The original plan allocated ₩1.5 trillion to debt repayment and ₩900 billion to next-generation solar capital expenditure (perovskite tandem cells and TOPCon capacity ramp). The final ₩1.2 trillion covers only part of that ambition. The company stated it will fund the remainder from internal resources and additional US-based liquidity. A parallel self-rescue plan is already underway: in June 2026, Hanwha Q CELLS's US subsidiary issued ₩300 billion in redeemable convertible preferred shares (RCPS) — a hybrid instrument booked as equity rather than debt.
Subscription Price in Context
At ₩22,100, existing shareholders face a meaningful dilution decision:
| Price Point | ₩ | vs. ₩22,100 |
|---|---|---|
| Preliminary issue price (May 2026) | 27,900 | –20.8% |
| July 20 market price (approx.) | ~32,000 | –30.9% |
| 52-week high | 59,300 | –62.7% |
| Analyst 12-month consensus target | 51,406 | –57.0% |
For investors willing to subscribe at ₩22,100, the discount looks substantial relative to the analyst consensus target of ₩51,406 — roughly 60% above current trading levels — though reaching that target depends on US operations normalising and IRA credits remaining intact.
What Analysts Are Saying
- Samsung Securities (Hold): IRA tailwinds and Hanwha Qcells recovery are largely reflected in the share price after the stock's 41% surge in May. Q3 US plant utilisation is the key variable.
- IBK Investment & Securities (Short-term Trading Buy): The reduced offering removes some dilution overhang, but the financing gap raises questions about the pace of solar capex.
- Hanwha Investment & Securities (Bullish): North American manufacturing positioning and emerging space-solar contracts are seen as underappreciated growth drivers.
Three Things to Watch
- Subscription rate (July 22–23): If take-up falls below 100%, unsubscribed shares go to the public. Weak demand would signal limited shareholder confidence and could weigh on the share price ahead of the August 11 listing.
- US operations in Q3 2026: Hanwha Qcells' Georgia plant returning to full utilisation is the central earnings catalyst. A miss would complicate the company's debt-reduction math.
- Additional funding disclosures: Management has flagged further US-based capital raises. Any new announcement — another RCPS tranche, asset monetisation, or DOE draw — will clarify the full roadmap.
This article is based on disclosures filed with South Korea's Financial Supervisory Service, Korea Herald reporting (July 20, 2026), Seoul Economic Daily, and public financial statements. It does not constitute investment advice. Hanwha Solutions (009830.KS) is a publicly listed company on the Korea Exchange.