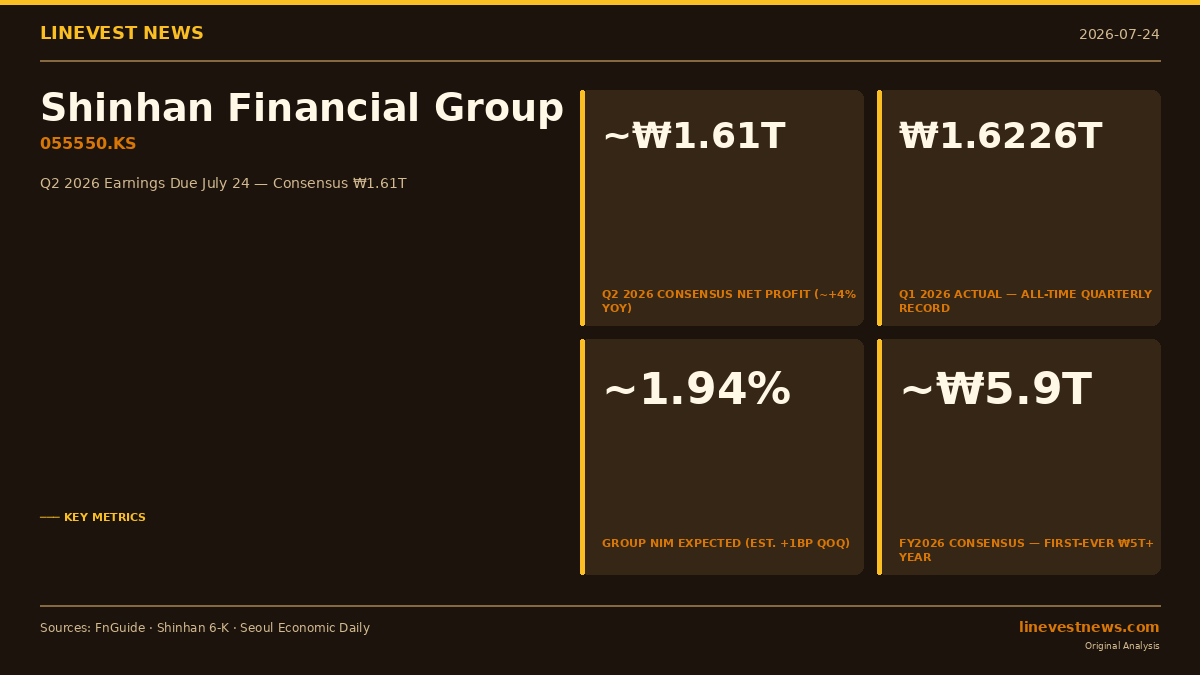
TL;DR - Q2 results on July 24 (before KRX open); sell-side consensus net profit ~₩1.61T (~+4% YoY) - H1 2026 cumulative profit projected at ~₩3.23T — the group's highest ever semi-annual result - BoK's July 16 +25bp hike (benchmark now 2.75%) is a forward tailwind for Q3/Q4 NIM — not captured in Q2 - Lotte Non-Life Insurance deal at ~₩1T: Shinhan is frontrunner; management commentary on July 24 is the key wildcard
Part A: What to Expect on July 24
Shinhan Financial Group (055550.KS; NYSE: SHG) is scheduled to release its preliminary Q2 2026 earnings on July 24, completing Korea's big bank earnings week alongside KB Financial (July 23) and Hana Financial (July 24 afternoon).
The group set an all-time quarterly record in Q1 2026, posting net profit attributable to parent shareholders of ₩1.6226T (+9.0% year-on-year as officially reported), supported by an exceptional surge in non-interest income. For Q2, the sell-side consensus compiled by FnGuide (as of July 14) stands at approximately ₩1.61T, implying roughly flat sequential movement but a modest ~+4% year-on-year gain over Q2 2025's ₩1.549T.
| Metric | Q2 2025 | Q1 2026 | Q2 2026E |
|---|---|---|---|
| Net profit (parent) | ₩1.549T | ₩1.623T | ~₩1.61T |
| YoY growth | — | +9.0%* | ~+4% |
| Group NIM | — | 1.93% | ~1.94% (+1bp) |
| Bank NIM | — | ~1.60% | ~1.61% (+1bp) |
| CET1 ratio | — | 13.30% | ~13.5% (est.) |
*As officially reported by Shinhan Financial Group in its Q1 2026 6-K filing.
Sources: Shinhan Financial Group 6-K SEC filings, FnGuide consensus as of July 14, 2026, iM Securities estimate.
Why Flat QoQ?
Q1 2026 featured an exceptional non-interest income spike: Shinhan Investment Corp (securities subsidiary) posted quarterly net profit of ₩288.4B (+167.4% YoY), and non-interest income across the group surged +106.7% quarter-on-quarter to ₩1.1882T — driven by a buoyant Korean equity market in January–March. Q2's comparison base normalises this effect, with securities income expected to step down toward a ₩150–200B range.
NIM: Organic Lift, Rate Hike Upside Deferred
The +1bp NIM improvement to ~1.94% at the group level (bank NIM ~1.61%) reflects loan repricing in the April–June interest rate environment, before the Bank of Korea's July 16 decision. The BoK's +25bp hike to 2.75% — its first in 3.5 years — falls outside Q2 and will benefit Q3 and Q4 NIM with a 1-2 quarter lag.
Part B: What This Means for Investors
1. H1 Record and the ₩5T Annual Milestone
If Q2 net profit lands near consensus, H1 2026 cumulative profit would reach approximately ₩3.23T. Full-year FY2026 consensus stands at ~₩5.9T, which would mark the first time in Shinhan's history that annual net profit has exceeded the ₩5T threshold.
For context, FY2025 net profit came in at ₩4.972T. The implied H2 2026 consensus of ~₩2.67T is sequentially lower than H1's ₩3.23T — reflecting non-interest income normalisation after Q1's exceptional securities performance — but materially above H2 2025's ~₩1.94T on a year-on-year basis, supported by a relatively low 2025 comparison base and incremental NIM gains from the rate cycle.
2. Value-Up 2.0 and Capital Returns
Shinhan's Value-Up 2.0 plan, launched in May 2026, targets: - ROE: 10–12% (long-term) - Payout ratio: 50%+ (ongoing) - CET1: ≥ 13% (floor)
The group achieved a 50.2% total shareholder return ratio in FY2025. Q1 2026 quarterly cash dividend was ₩740 per share (record date April 30; payment May 29). A Q2 dividend at a similar or modestly higher level is anticipated alongside the July 24 earnings release.
CET1 at 13.30% (Q1 end) is expected to improve toward ~13.5% by Q2 end, barring any large acquisition. That capital buffer supports additional H2 capital return capacity — a dynamic also flagged by KB Financial, which tied its ₩800B H2 buyback plan to CET1 progression.
3. The Lotte Non-Life Wildcard
The most significant near-term catalyst — or risk — is Shinhan's potential acquisition of Lotte Non-Life Insurance, currently owned by private equity firm JKL Partners.
As of mid-July 2026, Shinhan is widely understood to be the frontrunner, having delivered a non-binding price proposal. JKL Partners is seeking approximately ₩1T for the asset, citing Lotte Non-Life's total assets of ~₩14T. Shinhan's management has reportedly expressed price resistance, and formal due diligence has not yet commenced.
Shinhan currently lacks a major non-life insurance subsidiary — a gap versus KB Financial Group, which owns KB Insurance. A successful acquisition would complete the group's non-banking portfolio. However, at ~₩1T, the deal would reduce CET1 by an estimated 15–20bp, which management will need to weigh against the plan's ≥13% CET1 floor commitment.
Any formal announcement — or a definitive statement that Shinhan will not proceed — at the July 24 earnings call is likely to be a significant near-term share price mover.
4. BoK Rate Hike: A Q3/Q4 Earnings Catalyst
The Bank of Korea's July 16 rate hike to 2.75% — the first increase in 3.5 years, voted 7-0 — does not affect Q2 results, but it is a clear H2 earnings catalyst. Market consensus projects one additional +25bp hike before year-end, pointing to a 3.00% benchmark rate by Q4 2026.
Each +25bp move adds roughly 1–2bp to Korean bank group NIMs with a 1–2 quarter lag. Shinhan's NIM sensitivity to rate moves, and management's updated H2 NIM guidance, will be closely watched on July 24.
On the day of the BoK decision (July 16), Shinhan Financial's KRX-listed shares rose approximately 6% — a signal that the market views the rate cycle as a meaningful positive for the group's earnings trajectory.
5. Non-Interest Income: Can It Stay Above ₩1T?
The structural question is whether non-interest income can sustain levels above ₩1T quarterly. Shinhan Investment Corp's Q1 performance depended on elevated equity market activity and deal flow. If Q2 equity market conditions were less supportive than Q1, non-interest income could revert toward more normalised levels, creating a divergence between the headline earnings story and the underlying trend.
Management commentary on fee income trajectory, wealth management growth, and Shinhan Investment Corp's Q2 pipeline will be key read-throughs for H2 non-interest income sustainability.
The Bottom Line
Shinhan Financial enters Q2 earnings as one of Korea's most visible Value-Up plays, with a 50%+ shareholder return commitment, stable capital ratios, and a BoK rate tailwind building into the second half. The near-term upside catalyst is the Lotte Non-Life deal resolution and H2 rate path; downside risk is a deeper-than-expected normalization in securities income or a CET1-costly acquisition.
At FY2026 consensus of ~₩5.9T, Shinhan would cross the ₩5T annual profit threshold for the first time in its history — a symbolic milestone that may catalyze further re-rating under Korea's ongoing Value-Up corporate governance reform.
Sources: - Shinhan Financial Q1 2026 SEC 6-K Filing - Shinhan Q1 2026 Earnings Call Transcript - Lotte Non-Life Still Pricey as Shinhan Haggles Over Deal — Seoul Economic Daily - Shinhan Financial Launches Value-Up 2.0 — Seoul Economic Daily - 신한금융 2분기 컨센서스 — SAT Economy (FnGuide 컨센서스 인용) - Shinhan Financial Expected to Post Earnings on Friday — MarketBeat
Disclaimer: This article is for informational purposes only and does not constitute investment advice. LineVest News is an independent financial news publication and is not registered as an investment adviser. All figures cited are derived from public filings, FnGuide consensus data, and third-party analyst reports. Past performance is not indicative of future results.